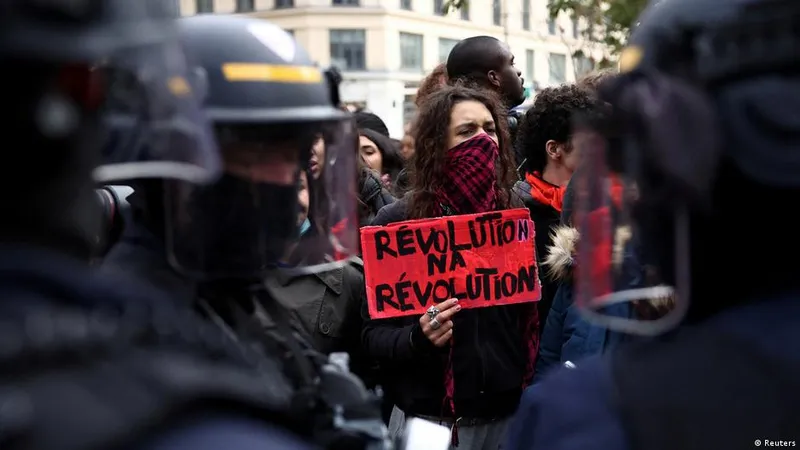
Amid protests, France's rising debt costs threaten stability
France's public debt stands at around 120% of GDP, forcing the government to pay higher interest rates than Germany as the risk premium on bonds reaches its highest level since the financial crisis.
France's current predicament is marked by deep indebtedness, political standoff between extremes, and a government without a parliamentary majority. The government plans to provide €4 billion in low-interest loans to renovate schools by 2030 and allocate a further €1 billion to universities by 2029, promising money the state simply does not have.
By comparison, Germany's debt-to-GDP ratio stands at roughly 65%, despite its €600 billion investment package for infrastructure and defense. While Germany maintains the highest possible AAA credit rating with a stable outlook, France is rated AA, A+ or Aa3, with several agencies assigning it a negative outlook.
As a result, France must pay higher interest rates on its borrowing than Germany. The risk premium over German government bonds, known as the spread, is now at its highest level since the financial crisis, with France paying nearly 1.6 percentage points more in interest than Germany on 10-year bonds.
Debt crisis warning
The spread acts as a kind of "fever gauge" for bond markets, explained Friedrich Heinemann, an economist at the Leibniz Center for European Economic Research (ZEW) in Mannheim.
This fever gauge then forces a change of course. If the spread rises too sharply, France's financing conditions come under pressure, and anyone in France who needs a loan has to pay higher interest rates. Banks then get into trouble, and the crisis escalates further.
He warned that this could slide toward a financial crisis, which would finally send a clear signal that "things cannot continue like this unless you are prepared to risk a genuine economic collapse."
Landry Charrier, a researcher at the University of Bonn's Center for Advanced Security, Strategic and Integration Studies, does not expect France's debt-fueled spending spree to end soon, noting that 56% of the French population receive more in government benefits and services than they pay in taxes and social contributions.
Rising interest burden
France last paid a similarly high-risk premium at the end of 2011, during the eurozone debt crisis. The spread over German government bonds has more than doubled since June 2026, driven by high debt levels, political instability, large budget deficits, and recent unrest.
France is expected to pay more than €79 billion in interest on its total public debt in 2026, with the figure projected to exceed €91 billion in 2027 and reach between €125 billion and €132 billion by 2030. The central government's interest bill alone is currently estimated at €62.6 billion.
In the coming years, France will have to refinance large amounts of outstanding bonds issued when interest rates were at historic lows while taking on additional debt due to its substantial budget deficit.
The trend is also affecting Germany. Heinemann has calculated that German interest payments are likely to triple within a few years, potentially exceeding €90 billion for the federal budget alone.
Political challenges
In France, economic realities seem to have little impact on political debate. Both the far-right National Rally (RN) and the far-left France Unbowed (LFI) are campaigning on costly promises. RN leader Marine Le Pen wants to reinstate the retirement age of 62 while promising €140 billion in savings.
Jean-Luc Melenchon, LFI's leader, has even suggested that government bonds held by the French central bank should be "thrown into the fire," claiming "nobody will ever notice they've disappeared."
For Heinemann, this is "a good example of radical parties on both the right and the left simply telling economic fairy tales." Their common message, he said, is that "there is a way out of this mess that requires neither fiscal consolidation nor painful cuts."
Charrier believes many French people have yet to grasp the seriousness of the situation, noting that "the euro has made it easier for France to access cheap financing and has long softened the pressure to adjust."
Related

